Financing
How In-House Financing Works at My Simple Living (No Credit Pull)
No outside lender, no credit pull, no SSN. Here's exactly how our in-house financing works, from pre-qualifying to picking your term.
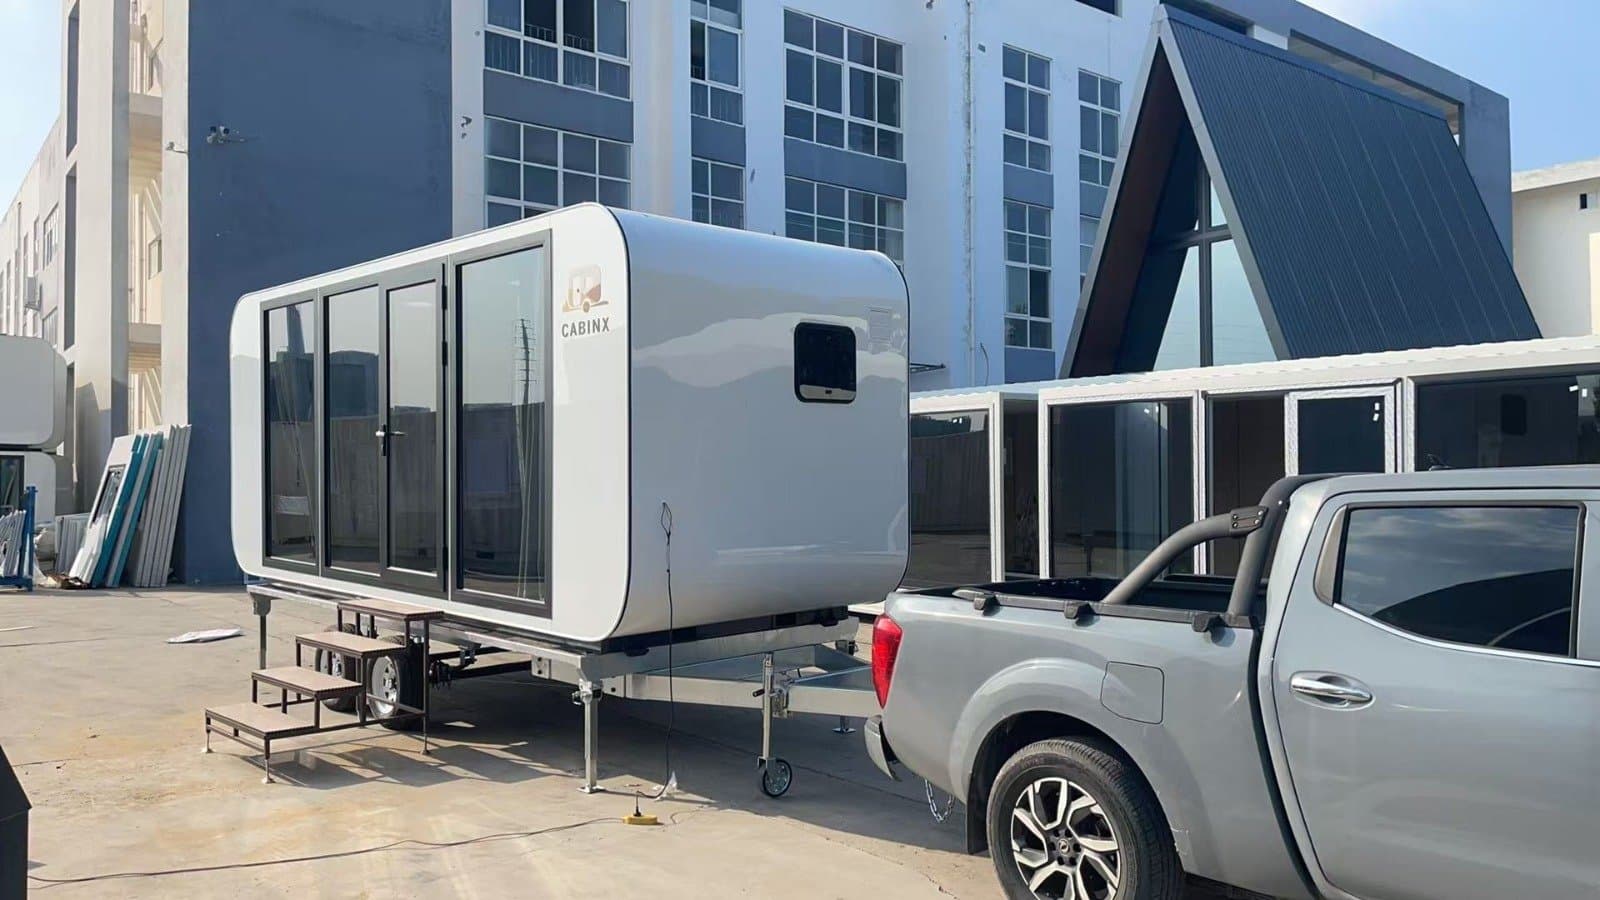
Buying a tiny home or ADU usually means one of three paths: pay cash, go through an outside lender (a personal loan, an RV loan, or a construction or chattel loan), or use a seller's own in-house financing. We offer the third option directly; there is no outside bank or finance company involved.
How pre-qualification works
Our pre-qualify tool is built around one rule: the only thing that decides approval is your down payment. There's no credit pull, no Social Security number collected, and no impact on your credit score. You tell us your gross yearly income, how much you'd like to finance, and whether there's a co-borrower; the tool checks that against the model's minimum down payment and gives you an answer in about 60 seconds.
Income, job history, and whether you own or rent are asked only so our team has context for the follow-up call. They don't change the decision. The down payment is what we're actually underwriting on.
The terms
- A fixed 10% APR, the same rate regardless of the amount financed.
- Terms up to 36 months. After you're approved, you choose from the available terms; the longer the term, the lower the monthly payment, the more total interest.
- A minimum down payment set per model, shown on each model's page and in the pre-qualify result, since it varies by unit.
- The amount you finance is capped at the model's price minus its minimum down payment, so you can't be offered more financing than the home actually costs.
What happens after approval
Once approved, you pick a term, your down payment is calculated automatically (price minus the amount financed), and that choice carries through to the configurator so your numbers stay consistent all the way to checkout. Final terms are always confirmed in writing before anything is signed.
Financing and delivery, together
Delivery is priced separately from financing: currently $1.50 per road mile with a $500 minimum, calculated from our Hurricane, Utah location. We ship to all 48 contiguous states, but because the rate is per mile, buyers within a few hundred miles of Hurricane, across Utah, Nevada, Arizona, Idaho, and the surrounding Mountain West, naturally see the lowest delivery costs. If a crane, special permits, or difficult site access are involved, those are quoted separately and never hold up your order; you pay those costs directly to the operators who do the work.
How this compares to other financing paths
If you've looked at financing a tiny home or ADU elsewhere, you've probably seen three general categories: a personal loan (fast, but usually a hard credit pull and a shorter term), an RV-style loan (sometimes used for park-model and towable units, typically requiring a credit application), or a construction or chattel loan tied to the land (slower, more paperwork, often used for larger or permanently-foundationed ADUs). Our in-house program is closest in spirit to a simple retail installment plan: no outside underwriter, a fixed rate, and a decision based on what you put down rather than a credit file.
Ready to check your number?
Use the pre-qualify tool on any model page, or contact us if you'd rather talk it through first.
Frequently asked
Does pre-qualifying affect my credit score?
No. We don't pull credit or collect a Social Security number at pre-qualification. The decision is based on your down payment.
What's the interest rate and how long can I finance?
A fixed 10% APR, with terms up to 36 months. You choose your term after you're approved.
Can I finance the full price with no down payment?
No. Every model has a minimum down payment, shown on its product page, and the amount financed is capped at the price minus that minimum.